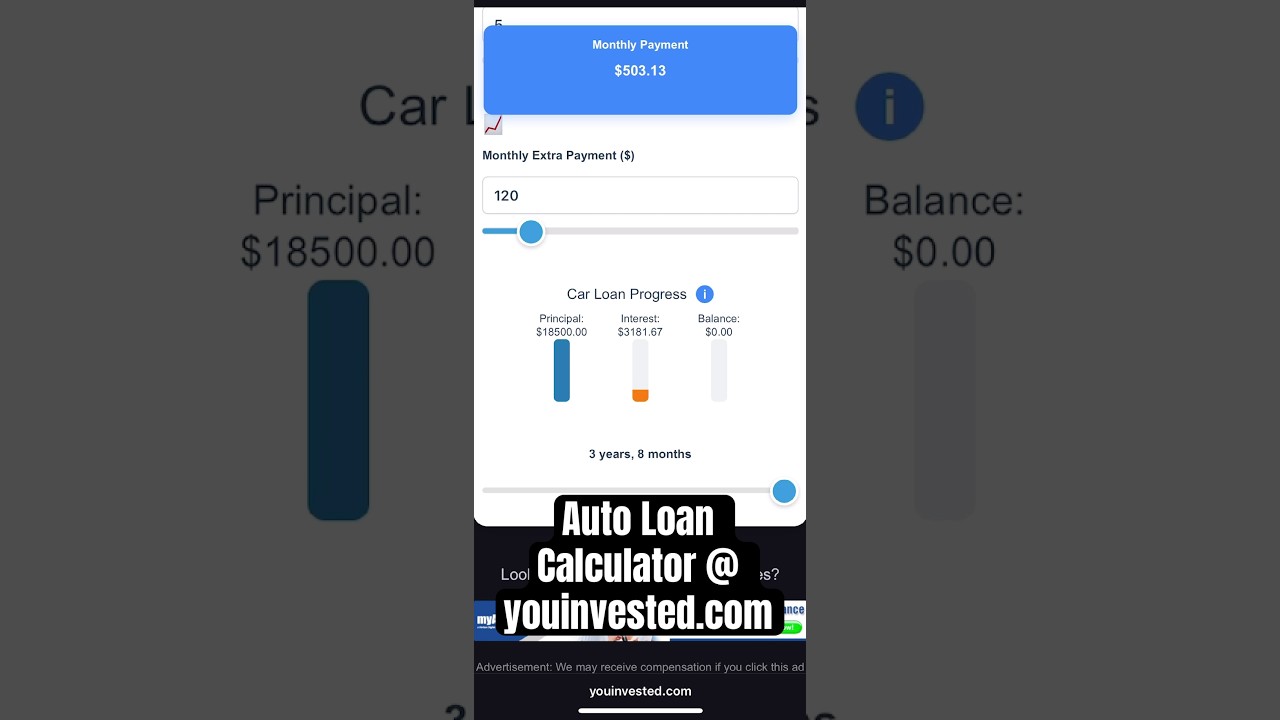
Interactive Auto Loan Calculator

Monthly Payment

$0.00

Total Interest

$0.00

Total Amount

Principal + interest

$0.00

πŸ’°
πŸ’Έ
%
⏳
πŸ“ˆ

Car Loan Progress

i

Principal: $0.00

Interest: $0.00

Balance: $0.00

Month 1

You Invested in your next carβ€”plan smart with our real-time Auto Loan Calculator! Adjust the car price, down payment, loan term, or interest rate, and see your monthly payments update instantly. Drive toward financial success with our timeless auto financing strategies that help you make smart vehicle decisions while building long-term wealth.

See How It Works

Watch our quick demo to see how the interactive auto loan calculator helps you explore different loan scenarios and make smarter car financing decisions.

Click to watch on YouTube β†—

10 Essential Auto Loan Tips

1. Shop Around for Rates

πŸ”+

Compare loan offers from banks, credit unions, and dealers to secure the lowest interest rate. Don't settle for the first offer you receive.

2. Check Your Credit Score

πŸ“Š+

Review your credit score before applying, as a higher score can get you better loan terms. Consider improving your score if needed.

3. Consider Loan Terms Carefully

⏱️+

While longer terms (72-84 months) offer lower monthly payments, you'll pay significantly more interest. Use our calculator to compare total costs and ensure you're getting the best deal.

4. Keep the Loan Term Short

⏰+

Opt for the shortest loan term you can afford to reduce total interest paid. Longer terms mean more interest over time.

5. Make a Large Down Payment

πŸ’°+

Put down at least 20% to lower the loan amount and monthly payments. This also helps avoid being upside-down on your loan.

6. Avoid Upselling

🚫+

Decline unnecessary add-ons like extended warranties or gap insurance if you don't need them. These can significantly increase your loan amount.

7. Understand Total Costs

πŸ’‘+

Factor in interest, fees, taxes, and insurance when budgeting for the car. The sticker price is just the beginning of your expenses.

8. Pay More Than Minimum

πŸ“ˆ+

Make extra payments toward the principal to pay off the loan faster and save on interest. This can significantly reduce your total cost.

9. Consider Refinancing

πŸ”„+

If rates drop or your credit improves, consider refinancing to get a lower rate. This can save you money on interest.

10. Read the Fine Print

πŸ“„+

Review all loan terms, including prepayment penalties or hidden fees, before signing. Make sure you understand everything you're agreeing to.

Auto Loan Planning Guide

Explore common auto loan scenarios and get the most out of our calculator

Price, down payment or trade-in, rate, and term drive the payment. A longer term such as 72 months lowers the monthly bill and raises total interest; a larger down payment does the opposite. Enter a used-car price and a trade-in the same way you would for a new carβ€”the math does not change, only the numbers you type.

The calculator does not pull live credit-tier APRs or insurance quotes. For a weaker credit score or a refinance, type the rate a lender actually offered. Lease-versus-buy and total cost of ownership (warranty, insurance, maintenance) are shopping questions you can sanity-check by comparing the loan payment here with the other quotes you collect.

New vs Used Car Decision

"Comparing a $30,000 new car vs $20,000 used car? Calculate the true monthly difference including insurance..."

Lease vs Buy Analysis

"Thinking about leasing? Compare lease payments vs loan payments over 3-5 years..."

Refinancing Strategy

"Credit score improved since purchase? Calculate savings from refinancing your current auto loan..."

Trade-In Impact

"Trading in your old car? See how different trade values affect your new loan amount..."

Extended Warranty Decision

"Dealer offering extended warranty? Calculate how it affects your monthly budget..."

  • Before visiting the dealership
  • When comparing financing offers from dealers vs banks
  • Before deciding between new and used vehicles
  • When considering auto loan refinancing
  • Planning your total transportation budget
  • Comparing lease vs purchase options

Frequently Asked Questions

Get instant answers about auto loans and how our calculator can help you make wise financing decisions.

Our auto loan calculator provides real-time, live calculations that instantly update as you adjust any slider or input field. Unlike static calculators, our dynamic tool shows immediate results for monthly payments, total interest, and total loan cost, allowing you to explore dozens of scenarios in seconds.

Our calculator uses industry-standard formulas to provide highly accurate estimates. However, these are for planning purposes only. Your final loan terms will depend on your credit score, income, and the specific lender. Always consult with a loan officer for official terms.

Simply use the live down payment slider. As you increase the down payment, you will instantly see your loan amount, monthly payment, and total interest paid decrease. This helps you understand the powerful financial benefit of a larger down payment.

You can get auto loans from several sources, including banks, credit unions, online lenders, and dealership financing. Credit unions often offer some of the most competitive rates, so it's always wise to compare offers from multiple sources before making a decision.

Use the loan term slider to see the trade-offs instantly. A shorter term (e.g., 36-48 months) means higher monthly payments but you'll pay significantly less in total interest. A longer term (e.g., 60-84 months) gives you lower monthly payments, but you'll pay more in interest over the life of the loan. Consider your monthly budget versus the total long-term cost.

While AI can provide loan calculations, our interactive tool lets you compare loan terms, down payment amounts, and interest rates instantly to find your most affordable car financing option. See total interest costs, not just monthly payments. Adjust variables and see instant visual results - perfect for comparing options and making confident financial decisions. AI gives you an answer; our calculator helps you find your best option.

Use this calculator when you want to explore how different loan terms affect your monthly budget, see the true cost of different down payment amounts, or understand how much you'll really pay in total interest over the life of your car loan. While AI can give you basic payment calculations, our interactive tool shows you the complete financial picture with instant visual comparisons. Adjust variables and see instant visual results - perfect for comparing options and making confident financial decisions. AI gives you an answer; our calculator helps you find your best option.

Our calculator does this for you automatically! The "Total Interest Paid" metric in the dashboard shows you the complete cost of borrowing over the entire loan term. This number is crucial for understanding the true cost of your car beyond the sticker price.

Making extra payments reduces your loan principal faster. This means you will pay off your loan sooner and save a significant amount of money on total interest. Use the extra payment slider to see exactly how much you can save.

Interest rates vary based on credit score, loan term, and market conditions. Excellent credit (720+) typically qualifies for rates between 4.5% - 6.0%, while lower scores may see higher rates.

  • Superprime (781+): ~5.18% (New) / ~6.82% (Used)
  • Prime (661-780): ~6.70% (New) / ~9.06% (Used)
  • Nonprime (601-660): ~9.83% (New) / ~13.74% (Used)

Use our interest rate slider to see how these different rates would affect your payment.

Leasing often means lower monthly payments but you don't own the car, similar to renting vs. buying a home. Financing leads to ownership but with higher monthly payments. If you like driving a new car every few years and drive a predictable number of miles, leasing might be for you. If you want to build equity and have no mileage limits, financing is the better path. You can also explore home ownership costs with our mortgage calculator.

The 20/4/10 rule is a smart financial guideline for car buying. It recommends:

  • A 20% down payment.
  • A loan term of no more than 4 years.
  • Your total monthly car expenses (payment, insurance, etc.) should be less than 10% of your gross income.

Our calculator can help you model the first two parts of this rule perfectly.

Aiming for a 20% down payment is a great goal, as it helps prevent you from being "upside-down" (owing more than the car is worth). However, any amount you can put down will help lower your monthly payment and reduce the total interest you pay. Use our down payment slider to find a number that works for your budget.

Yes, it is possible to get a car loan with bad credit, but it will likely come with a significantly higher interest rate. A larger down payment can help improve your chances of approval. We recommend using our calculator to see how a higher interest rate will impact the total cost of your loan before you commit.

A good APR (Annual Percentage Rate) depends on your credit score and whether you're buying a new or used car. For a borrower with a prime credit score (661-780), a good APR would be around 6-9%. For superprime borrowers (781+), anything under 6% is excellent. The best way to find a good APR is to get pre-approved from multiple lenders.

AI provides static auto loan calculations, but our interactive tool lets you explore loan terms with sliders, see visual payment breakdowns, and compare different financing scenarios in real-time - all unavailable through AI text responses. When you want to explore how different loan terms affect payments, see the impact of various down payment amounts, or visualize total interest costs across different scenarios, our interactive tool is superior.